90% LTC
Plus get up to 100% of construction covered.
Draw process
Build your way with funds in as little as 24 hours.
A&D takeout
Refinance your land acquisition & go vertical.
Contractor experience
Get approved with your flip or GC record.

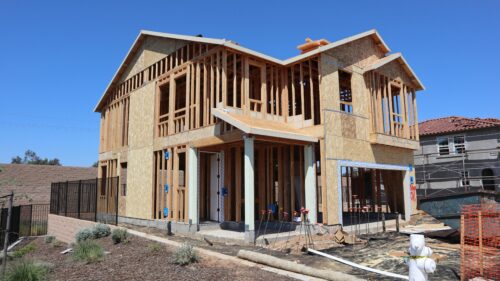
At Lima One, we know the challenges builders face in getting a property from plans to market. When you’re ready to start building, we’ll set your exposure, close as quickly as possible, and get you going vertical with minimal red tape.
Plus get up to 100% of construction covered.
Build your way with funds in as little as 24 hours.
Refinance your land acquisition & go vertical.
Get approved with your flip or GC record.
Tired of being slowed down by banks? We fund based on your builder experience and the strength of the proposed asset.
Building to sell, rent, or refinance? Forget one-size-fits-all. Our flexible loan structuring is designed to support your unique project.
When you’ve maxed out at your bank, we can help you keep the momentum. Our high exposure limits help you unlock more projects at once.
Already own the land or finished horizontal development? We can help turn your equity into capital for vertical construction.
Construction timelines, exit strategies, and market conditions do not always move in a straight line. With Build2Rent® and Bridge financing, Lima One gives builders more flexibility to hold, refinance, or create extra runway when the project calls for it.
Project Types
As experienced new construction lenders, we work with builders of all types, and we’ve seen just about every kind of residential construction project. That means we’re comfortable with a wide variety of projects and strategies. It also means we know how to provide financing across a broad spectrum of construction projects without holding you back.
You’ve got a knack for building houses that appeal to buyers in your market. We have a knack for finding the new construction loan solution that maximizes your profit.
Removing a distressed property and building a beautiful new home in its place is a great way to improve a neighborhood and add new inventory to the market. Yes, we finance this strategy — with new construction loans for savvy investors designed for long-term community impact.
If you have a vision for building small or medium developments — or sections of larger developments — on available land, our team will help you figure out the scope of the project and the best.
From affordable homes with builder-grade finishes to high-end properties with custom finishes, we can finance new construction at any price point. We're no strangers to developing new construction loans for custom and luxury homes.
Do you have an entitled lot that simply needs financing? Whether it's in an urban or suburban area, our new construction loans allow investors to take an opportunity that’s in a development and build a new property within an existing neighborhood.
Construction Draws
Keep the work moving and the contractors happy. Whether you’re building a new single-family home or breaking ground on a new development, our draw process is designed for speed, so you can execute on your terms.
If you’ve ever tried to get new construction financing through a traditional bank, you know the frustrations of wading through endless documentation, verifications, and approvals. We’re not saying banks get it wrong — we’re just saying we do things differently.
Quick and Easy
Complex and Time Consuming
A new construction loan can fund both the lot acquisition cost and the actual construction on the lot. Lima One funds vertical construction including ground-up new builds and tear down/rebuild projects. Lima One does not fund horizontal construction, which means land must be properly zoned, and municipal utilities must be lateral ready for the property to qualify. Lima One requires investors who take out new construction loans to have experience with ground-up projects, either on title, as a general contractor, or with fix and flip projects. A Lima One loan consultant can help investors analyze their specific experience to see if they qualify for construction financing. Completing the borrower underwriting steps will enable Lima One to close construction loans more quickly when a loan is submitted.
The key parts of preapproval for a Lima One construction loan can happen with or without an actual build that is ready to start. First, a borrower must qualify for a new construction loan based on experience with new construction, either on title or as a general contractor, or with fix and flip projects. Second, a borrower must demonstrate liquid assets so Lima One can establish a credit exposure limit. This limit is valid for six months and can apply to one project or multiple projects. Third, a borrower will need to agree to a soft credit score pull. Note that a hard credit pull will be required once a loan is submitted.
For the most experienced builders, Lima One will cover up to 85% of the blended costs of a build. This includes up to 100% of the construction costs and up to 60% of the lot costs. Borrowers with less experience should expect to put more money down at the start of a loan.
A construction to permanent loan solution is designed for a build-to-rent project. The construction loan covers the build, and then the borrower refinances into a DSCR loan to hold the property as a rental once a tenant is in place. Lima One’s Build2Rent® loan program offers both types of loans, with no seasoning required to refinance into a rental loan. It also offers an origination fee discount for the rental loan.
A borrower will need to provide building plans, a line-item construction budget, and other documentation via a property application. Lima One’s in-house team will review the budget to ensure it is sufficient and appropriate for the project in view. Lima One will also conduct a general contractor review as part of the underwriting process.
Lima One new construction loans have a standard length of 13 months. 19-month terms are also available.
Foreign nationals can qualify for ground-up construction loans, even if they do not have an established credit score. A Lima One loan consultant can provide more information about what a foreign national or permanent resident alien needs to do for borrower underwriting.
Construction insights for builders